
Last Updated: November 1, 2026
Quick Summary
Business credit accounts let you receive supplies now and pay later, usually within 30 days, so cash stays in the business for roughly a month to cover payroll, rent or unexpected repairs. For SMEs ordering stationery, janitorial products, catering goods and workwear on a repeating cycle, these accounts help plan purchasing more evenly.
- Thirty-day terms mean payment is due 30 days from the invoice date, not the order date.
- Supplier trade accounts usually carry no interest if you pay within terms.
- A 2% discount for paying within 7 days on £2,000 monthly supplies saves £40 a month.
- Set spending limits per authorised user and review the account statement weekly, not monthly.
- Cap each authorised user's spending limit and diarise invoice due dates when stock arrives.
Table of Contents
- Why Business Credit Accounts for Supplies Change Your Cash Flow
- How to Apply for a Business Credit Account
- 30 Day Payment Terms for Business Supplies: What to Expect
- Business Credit Account vs Business Credit Card
- The Total Cost of Credit: Fees, Interest and Discounts Lost
- Keeping Records Clean: Expense Tracking and Reconciliation
- Risks and Responsible Use of a Trade Account
- Create Your UK Business Supplies Account
- Frequently Asked Questions
Why Business Credit Accounts for Supplies Change Your Cash Flow
A business credit account is a supplier arrangement that lets you receive supplies now and pay for them later, usually within an agreed window such as 30 days. For most SMEs, the appeal of business credit accounts is simple: stock arrives when you need it, but cash leaves the business weeks later. Businesses that order stationery, janitorial products, catering goods and workwear on a repeating cycle can use these accounts to plan their purchasing more evenly.
The cash-flow effect is the real story. Money that would have left your account on delivery day stays in the business for another month, covering payroll, rent or an unexpected repair. Under GOV.UK guidance on business cash flow and late payment, managing the timing of payments in and out is a core discipline for small firms, and supplier terms sit right at the centre of it. Below, we break down how to apply, what 30-day terms actually mean, how a trade account compares with a credit card, and where the hidden costs sit.
How to Apply for a Business Credit Account
Applying for a supplier credit account usually takes one form and a short wait for approval.
Documents and details to have ready
- Company name, registered address and company number
- VAT registration number, if applicable
- Contact details for the person managing the account
- An estimate of monthly supply spend
What suppliers check before approving a limit
A supplier is extending you unsecured credit, so the check is about risk. A common mistake is asking for a limit far above your actual spend. Start modest, pay on time, and request an increase once the record exists.
30 Day Payment Terms for Business Supplies: What to Expect
Thirty-day terms mean the invoice lands on delivery and payment is due 30 days from the invoice date, not from the day you ordered. In practice, this gives you roughly a month of working capital headroom on every order.
The detail that catches people out is the invoice date itself. Some suppliers date invoices from dispatch, others from month end. Ask which applies before you sign, because it shifts your real payment deadline by days.
Business Credit Account vs Business Credit Card
A supplier trade account and a business credit card both defer payment, but they solve different problems. A supplier trade account is tied to one vendor and typically carries no interest if you pay within terms. A business credit card works anywhere that accepts cards and often pays rewards, but it charges interest on any balance you roll over. A business line of credit sits between the two: it is a revolving facility you can draw on for any supplier, but it usually charges interest from the day you draw and may carry an arrangement fee.
For supply-heavy purchasing, the right tool depends on your order pattern, not on which product sounds most flexible. The table below sets out the practical differences across the three options most SMEs consider.
| Feature | Supplier trade account | Business credit card | Business line of credit |
|---|---|---|---|
| Where you can spend | One supplier's catalogue | Anywhere cards are accepted | Any supplier, once drawn |
| Interest | Usually none within terms | Charged on carried balances | Charged from drawdown |
| Typical terms | 30 days from invoice | Statement cycle, minimum payment | Revolving, interest on used amount |
| Best for | Recurring supplies from one source | Mixed spending and travel | Bridging gaps across multiple suppliers |
| Rewards | Occasional settlement discounts | Cash back and travel perks | Rarely any |
| Application burden | Supplier form and references | Card issuer checks | Fuller underwriting and fees |
For supply-heavy purchasing, a trade account is usually the cleanest tool for repeat orders from one supplier. A card earns rewards but can lead to revolving debt if a balance is carried, and a line of credit suits short bridging across several suppliers rather than routine stock orders.
The Total Cost of Credit: Fees, Interest and Discounts Lost
A trade account can carry costs worth pricing in. Late payment charges, administration fees and early settlement discounts you forfeit by paying at day 30 instead of an earlier date all count, and some suppliers offer a small percentage off for prompt payment.
A simple worked example makes the trade-off concrete. Suppose a supplier offers a 2% discount for payment within 7 days, and you order £2,000 of supplies a month. Paying early would save £40 a month, but only if you actually pay early every time; missing the early window once can erase the benefit.
5 Star A4 Analysis Pad 8 Cash Column 80 Sheets 70gsm 330291 →
The same logic applies to cards and lines of credit: interest on a carried balance can quickly outweigh a settlement discount, so compare the annualised cost of credit with the value of the discount. The practical rule is to compare the annualised cost of the credit with the annualised value of the discount, not the headline rate with the headline percentage.
Our advice: read the terms for the late-payment charge, any administration fee and the settlement discount before you commit. Ask the supplier which date the invoice runs from, because the invoice date affects your real payment window. For a wider view of where procurement spend leaks, see our guide to managing office supply procurement costs, which covers the full cost picture beyond the credit terms themselves.
Keeping Records Clean: Expense Tracking and Reconciliation
Clean records turn a credit account from a risk into an asset. Every invoice needs matching to an order and a delivery note, and every purchase needs a named person who authorised it. Without that discipline, maverick spending creeps in and month-end reconciliation becomes a scramble.
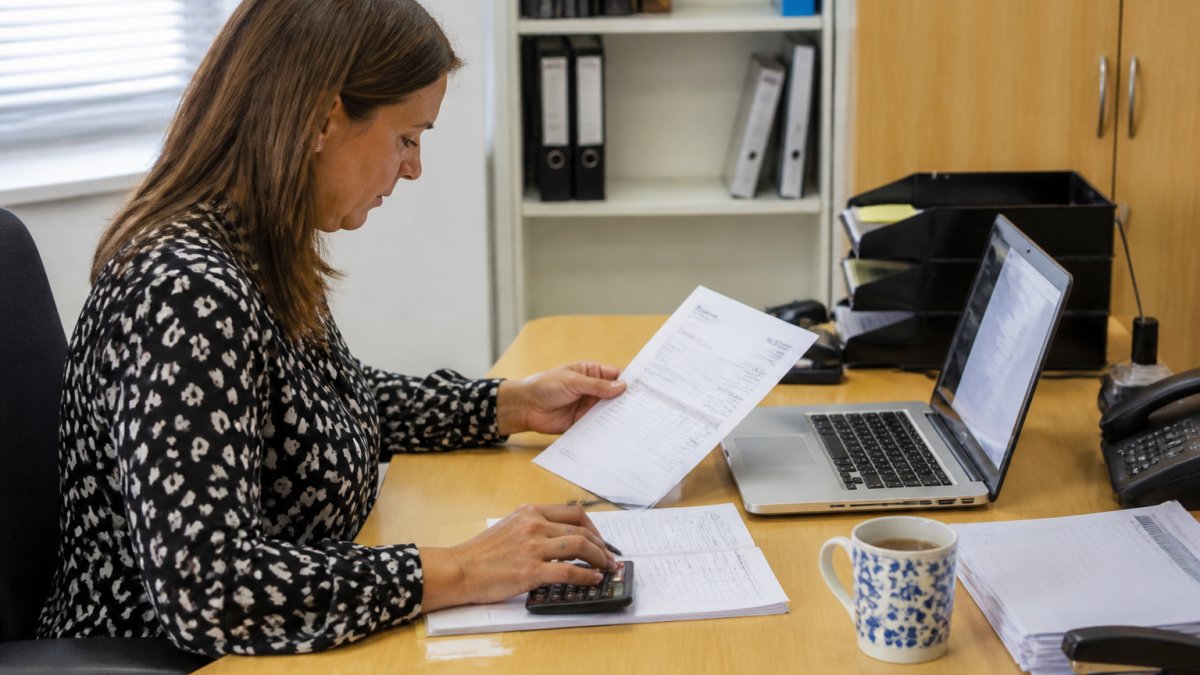
Manual tools still do this job well. A 5 Star Office Petty Cash Pad at £3.49 records the reason, value and authorising signature for small purchases, while a Collins Cathedral analysis book at £30.49 provides cash columns for recording money in and out. For teams tracking who ordered what against the account, our guide on how to track employee supply spending walks through the workflow. Set spending limits per authorised user and review the account statement weekly, not monthly.


Risks and Responsible Use of a Trade Account
A trade account is borrowed money, and it carries the same discipline as any borrowing. The main risks are over-ordering because payment feels deferred, missing a due date and losing the account, and letting one person control the whole spend with no oversight.
Guard against all three with simple rules. Cap each authorised user's spending limit. Diarise invoice due dates the moment stock arrives. Review the account monthly against your budget. Used this way, a trade account builds a payment record that strengthens your creditworthiness with other suppliers over time. Used carelessly, it becomes a quiet drain. For a fuller walk-through of buying supplies on credit, read our business guide to credit accounts.
Create Your UK Business Supplies Account
Consolidating stationery, janitorial, catering and workwear orders under one credit account can reduce the work of managing several suppliers and payment dates. We offer credit account options so you can order what the office needs and settle on agreed terms, with online ordering and delivery tracking in one place.
Opening an account starts with an application. Have your company details ready, and we will help you discuss the account options that fit your spend. To start, visit our contact page and tell us what you order and how often. Get started with UK Business Supplies and put your supply spend on terms that work with your cash flow, not against it.
Frequently Asked Questions
What are the benefits of a business credit account for supplies?
A business credit account lets you order stationery, janitorial products and catering supplies now and settle the invoice later, usually on 30 day terms. That keeps working capital free for payroll and rent instead of tying it up in stock. Consolidating orders under one account can make reconciliation and expense tracking simpler than juggling several separate orders.
How do I set up a business credit account with a supplier?
Start by contacting UK Business Supplies to discuss a credit account, and have your company details ready. Read the account terms before signing so you know the payment window and any charges that apply.
Can a business credit account help with cash flow?
Yes, mainly by shifting the timing of payments. If you order supplies on the first of the month and pay 30 days later, you have used the goods for a month before the money leaves your account. That gap matters for seasonal businesses and anyone with uneven invoicing. The benefit only holds if you pay in full by the due date, because interest and late charges on a missed payment can wipe out the advantage quickly.
What happens if a business misses a credit account payment?
Expect a late payment charge and possibly interest on the outstanding balance, both set out in your account terms. Late payment can lead to charges set out in your account terms. If you cannot pay on time, contact us before the due date to discuss your options.
